
Nigeria’s mobile technology ecosystem closed 2025 on a strong note, with fresh industry data pointing to a significant acceleration in device adoption across key urban and semi-urban markets. A new market intelligence report indicates that smartphone penetration continues to deepen, supported by affordable 4G models and expanding digital consumption patterns.
Nigeria smartphone shipments jump 25% – Report
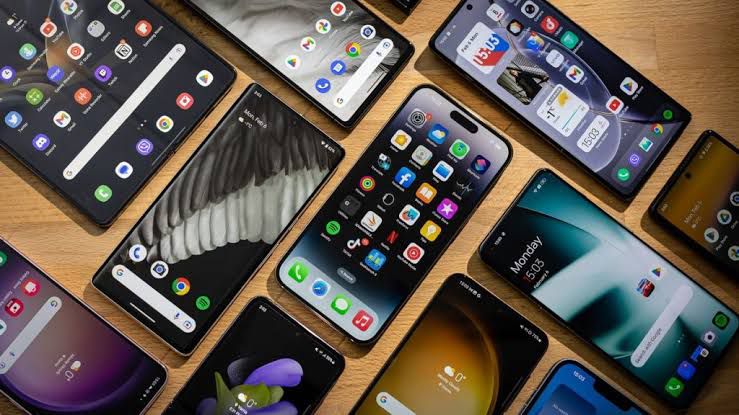
According to research by Omdia, Nigeria recorded a 25 per cent year-on-year increase in smartphone shipments in the fourth quarter of 2025.
The surge reflects heightened demand for entry-level smart devices, particularly in the sub-$200 category, where price sensitivity remains a defining characteristic of consumer behaviour.
The report shows that Nigeria’s performance forms part of a broader continental rebound.
Across Africa, smartphone shipments reached 23.1 million units in Q4 2025, marking a 14 per cent increase compared to the same period in 2024. On a full-year basis, total shipments climbed to 84.4 million units — a 13 per cent rise and the region’s strongest recovery since 2021.
Industry analysts attribute the Q4 expansion to sustained network investments, improved 4G coverage, and growing reliance on mobile data for financial services, entertainment streaming, and small business operations.
Entry-Level Devices Drive Growth
The Nigeria smartphone shipments jump 25% – Report finding underscores the centrality of affordability in the country’s device market. Smartphones priced below $200 accounted for the bulk of purchases, reinforcing Nigeria’s status as a value-driven ecosystem.
Despite rising component and logistics costs globally, manufacturers continued to compete aggressively in the entry-tier segment. However, analysts caution that margins are tightening, particularly for brands heavily exposed to ultra-low-price bands.
Principal Analyst at Omdia, Manish Pravinkumar, noted that Africa’s entry-level segment is facing mounting cost pressures. While demand remains resilient, maintaining affordability without compressing profitability may become more challenging in 2026.
Brand Competition Intensifies
Market share data reveal strong competition among original equipment manufacturers.
TRANSSION maintained leadership across Nigeria and several African markets, commanding a 44 per cent share despite modest growth of three per cent. Its portfolio, which includes multiple budget-focused lines, remains heavily concentrated in entry-tier devices.
Meanwhile, Samsung Electronics recorded its strongest quarterly performance since late 2021, expanding by 27 per cent. Growth was driven largely by its Galaxy A-series, which continues to resonate with mid-tier consumers seeking improved specifications without premium pricing.
Xiaomi Corporation also expanded by 12 per cent, leveraging localised marketing strategies and strengthened distribution partnerships. OPPO and HONOUR registered double-digit growth, consolidating their presence in Nigeria’s increasingly competitive retail channels.
The Nigeria smartphone shipments jump 25% – Report trend suggests that while established players retain dominance, challenger brands are steadily gaining traction through product differentiation and improved channel execution.
Transition from Feature Phones
Smartphones accounted for approximately 55 per cent of total handset shipments in 2025, reflecting continued migration away from traditional feature phones. This structural shift is reshaping Nigeria’s digital economy, as more consumers gain access to mobile banking, e-commerce platforms, and online education tools.
The ongoing transition is particularly pronounced among younger demographics and small-scale entrepreneurs who rely on smartphones for income-generating activities. Analysts argue that device penetration is directly linked to fintech growth, content streaming subscriptions, and digital advertising expansion.
The Nigeria smartphone shipments jump 25% – Report highlights how digital inclusion efforts are converging with private sector distribution networks to accelerate connectivity.
Pricing Trends and Inflationary Pressures
Average selling prices in Nigeria rose moderately during the period, mirroring broader continental trends. Increased semiconductor costs, currency volatility, and logistics expenses contributed to incremental price adjustments.
While the Q4 surge signals robust consumer appetite, industry watchers warn of potential headwinds in 2026. Inflationary pressures and constrained disposable income may prompt prepaid and first-time buyers to delay upgrades.
Maintaining equilibrium between affordability and channel inventory stability will be critical. Over-supply in a cost-constrained environment could trigger discounting cycles that erode profitability.
Comparative data show South Africa posting the strongest year-on-year performance among major African markets, with shipments rising 38 per cent, largely supported by prepaid demand. Kenya recorded more modest growth of three per cent, constrained by elevated living costs.
Nigeria’s 25 per cent quarterly surge places it among the continent’s fastest-growing smartphone markets. However, sustaining this pace will depend on macroeconomic stability, exchange rate movements, and consumer purchasing power.
The Nigeria smartphone shipments jump 25% – Report marks a milestone in the country’s post-pandemic technology recovery. Yet analysts remain cautious about replicating similar growth rates in 2026.
Manufacturers are expected to prioritise incremental hardware upgrades — including improved battery capacity, camera systems, and processing performance — within entry-level price brackets. Retail financing models and instalment-based purchasing schemes may also gain prominence as vendors seek to protect demand volumes.
For policymakers, expanding broadband infrastructure and stabilising macroeconomic conditions will be instrumental in sustaining digital adoption momentum.
As Nigeria’s smartphone ecosystem evolves, competition, affordability, and consumer adaptability will continue to shape shipment trajectories.
The Q4 surge demonstrates underlying demand strength, but the coming year will test the resilience of both vendors and buyers in a tightening economic climate.
About The Author